


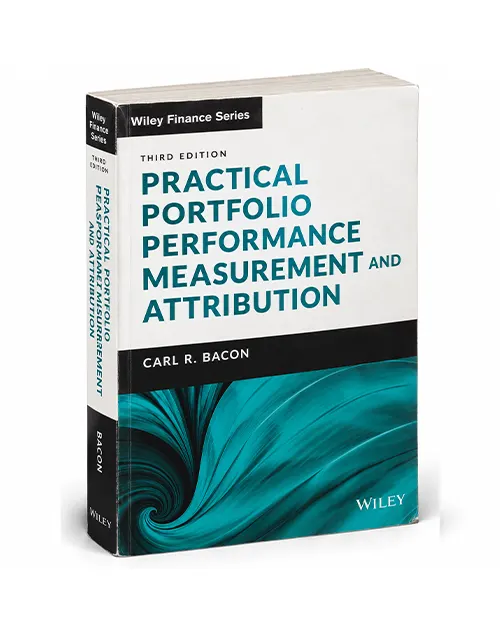
Evaluating an investment portfolio involves more than calculating its returns. Investors and asset managers also need to understand the sources of performance, the risks taken to achieve it, and the contribution of individual investment decisions. Practical Portfolio Performance Measurement & Attribution 3rd Edition (9781119831945) by Carl R. Bacon provides a practical reference for understanding these interconnected aspects of investment analysis. Published by Wiley in January 2023, this third edition is intended for professionals who work with portfolio evaluation, performance reporting, and investment management.
The book begins with the asset management industry and the different asset classes that portfolio professionals encounter, including equities, fixed income, private assets, real estate, commodities, derivatives, and hedge funds. It then develops the mathematical foundations of portfolio returns, explaining concepts such as time-weighted returns, money-weighted returns, internal rates of return, annualized performance, and gross-versus-net-of-fee calculations. These methods help readers understand how return figures are calculated and why the choice of measurement approach matters when evaluating investment results.
A substantial part of the book examines portfolio benchmarks, risk measurement, and return attribution. Readers can explore how benchmark selection influences performance comparisons, how risk measures help interpret investment outcomes, and how attribution analysis investigates the factors behind portfolio returns. Topics include asset allocation, security selection, multi-currency attribution, fixed-income attribution, multi-period analysis, and risk-adjusted attribution. The discussion connects mathematical methods with practical questions faced by investment professionals when assessing portfolio decisions.
Risk analysis receives detailed treatment through subjects such as volatility, tracking error, information ratios, regression analysis, factor models, drawdowns, downside risk, and risk-adjusted return measures. The book also addresses fixed-income risk, performance appraisal, and methods for examining the relationship between investment returns and the risks assumed. These concepts are relevant when comparing managers, reviewing investment strategies, or explaining why two portfolios with similar returns may have different risk characteristics.
Performance reporting is another important component of this edition. The text examines the Global Investment Performance Standards (GIPS), including their role in performance calculation, composite maintenance, disclosures, and presentation. Practical examples, worked calculations, and supporting Excel spreadsheets help readers engage with the quantitative aspects of performance measurement and attribution. Later chapters bring these subjects together through portfolio evaluation, manager selection, performance monitoring, dashboards, and risk control.
Practical Portfolio Performance Measurement and Attribution, Third Edition (9781119831945) is suited to portfolio managers, performance analysts, risk professionals, investment consultants, asset owners, and asset management teams. Finance students and researchers can also consult it when studying investment performance methodology beyond introductory portfolio theory. Its emphasis on calculations, attribution techniques, benchmarks, and reporting makes it particularly relevant to readers who need to interpret performance rather than simply report a return figure.
For professionals seeking a detailed reference on investment performance analysis, this Wiley publication connects return measurement, risk assessment, attribution, and performance presentation within one framework. If you need the third edition by Carl R. Bacon for professional development, research, or an investment management reference library, verify the hardcover format and ISBN 9781119831945 before ordering.
There are no reviews yet.